By Keith Eakes, REALTOR® | Sandbridge Life Realty Group
Formerly Outdoor Resorts of Virginia Beach
If you've been considering purchasing property at Surfside at Sandbridge, one of your first questions may be: "Can I get financing to purchase a property here?"
It's an important question, and one that deserves attention before you begin the buying process.
As a REALTOR® with Sandbridge Life Realty Group who has sold properties at Surfside, I understand that purchasing recreational resort real estate can involve considerations that differ from buying a traditional home.
Let's explore why financing can be challenging, what options may be available, and how to prepare for a successful purchase.
What Makes Surfside at Sandbridge Unique?
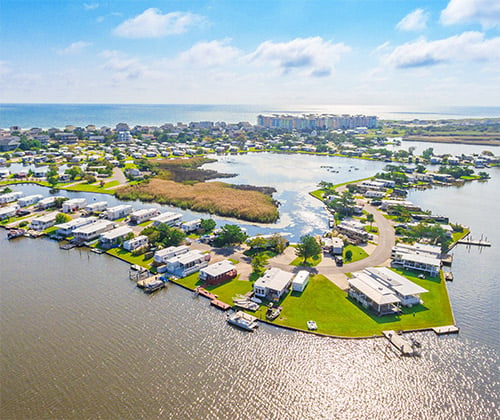
Surfside at Sandbridge, formerly Outdoor Resorts of Virginia Beach, is a gated recreational vehicle resort community located in the Sandbridge area of Virginia Beach.
Situated near the Atlantic Ocean and Back Bay, the community offers buyers an opportunity to enjoy a distinctive coastal lifestyle.
However, purchasing property at Surfside is not necessarily the same as purchasing a conventional residential condominium.
A transaction may involve a deeded RV condominium lot, an RV or park model, and other improvements.
Understanding precisely what is included in the sale is essential, particularly when financing is involved.
Why Can Traditional Mortgage Financing Be Difficult?
Many conventional mortgage programs have specific requirements concerning the type of property being financed.
Recreational vehicle lots, certain condominium projects, and properties with nontraditional improvements may not meet those requirements.
As a result, buyers who qualify financially for a conventional home mortgage may discover that the particular Surfside property they're considering does not qualify for the same financing program.
That doesn't necessarily mean financing is impossible. It means buyers may need to consider alternatives.
What Financing Options Should Buyers Explore?
Specialty Financing
Some lenders consider property types that fall outside traditional mortgage guidelines.
A buyer may wish to speak with a lender who has experience evaluating deeded recreational vehicle condominium lots.
Before applying, confirm that the lender will consider the specific property, not simply recreational properties in general.
Home Equity Loans or Lines of Credit
Buyers who own another home may have access to equity that could help finance a Surfside purchase.
A home equity loan or home equity line of credit may provide funding without requiring a traditional mortgage secured by the Surfside property.
However, borrowing against an existing home introduces risks, including the potential loss of that home if the loan is not repaid.
Seller Financing
In some transactions, a seller may be willing to finance a portion of the purchase price.
Seller financing terms are negotiated between the parties and may include a down payment, interest rate, repayment schedule, and balloon payment.
Availability varies by property and seller.
Buyers and sellers should consult appropriate legal and financial professionals before entering into such an arrangement.
Other Financing Arrangements
Depending on the buyer's circumstances, financing secured by other assets, personal loans, or a combination of cash and financing may be worth discussing with qualified financial professionals.
Every option should be evaluated for affordability, total borrowing cost, and repayment risk.
How Much Down Payment Will I Need?
There is no single down payment requirement that applies to every Surfside purchase.
The amount depends on the lender, financing structure, property characteristics, and buyer qualifications.
For example, on a hypothetical $250,000 purchase, a 25% down payment would equal $62,500, leaving $187,500 to finance.
This is simply an illustration, not a statement that a 25% down payment or any particular financing program is currently available.
Buyers should obtain actual financing terms before relying on any payment estimate.
Don't Overlook the Cost of Ownership
When evaluating a Surfside property, remember to consider expenses beyond the purchase price.
These may include condominium association fees, real estate taxes, insurance, utilities, RV maintenance, and special assessments.
Buyers should also review the applicable condominium documents and confirm occupancy, rental, vehicle, and improvement restrictions.
These factors can influence both the enjoyment of the property and the buyer's financial obligations.
My Recommendation: Explore Financing Before Making an Offer
One of the best things prospective buyers can do is investigate financing early.
Before committing to a purchase, understand what is included in the transaction and discuss the property with potential lenders.
As a real estate professional who has sold properties at Surfside, I can help buyers navigate the real estate aspects of the transaction, understand important property considerations, and identify questions to ask lenders and other qualified professionals.
I do not want buyers to assume that a traditional mortgage is their only possible financing option.
At the same time, no buyer should assume that financing will be available without first confirming the details.
Preparation, accurate information, and professional guidance can make a meaningful difference.
Ready to Explore Property Ownership at Surfside?
Whether you're beginning your search or have already found a property that interests you, understanding the financing considerations is an important first step.
I welcome the opportunity to discuss Surfside real estate with you and help you navigate the buying process.
Let's talk about your Surfside real estate goals.
Financing information is provided for general educational purposes. Loan programs, eligibility, rates, terms, and approval are determined by individual lenders. This article does not constitute a financing commitment or financial or legal advice.
This blog is an independent real estate publication and is not presented as an official communication from the Surfside condominium association.